Tax on share gains and STT: the CBDT chief says suggestions are being examined; no change has been announced
Long-term gains on listed shares are taxed at 12.5% above ₹1.25 lakh a year. In July the government told Parliament it had no proposal to scrap the tax; on 16 November the CBDT Chairman said the outcome would be known on 1 February.
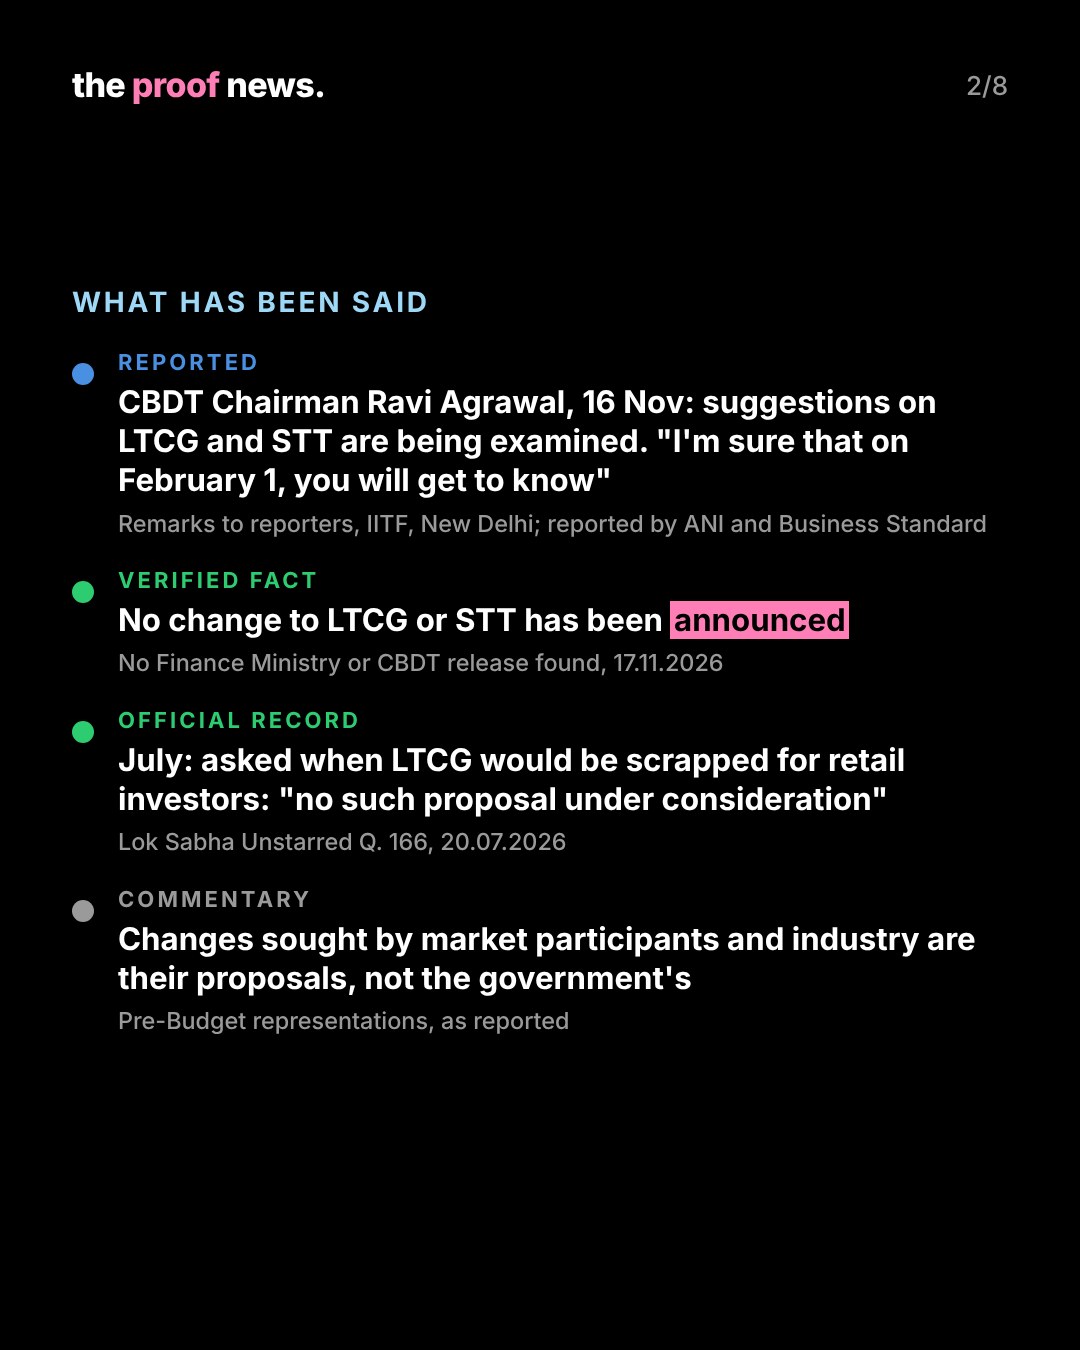
ReportedCBDT Chairman Ravi Agrawal, speaking to reporters after inaugurating the Income Tax Department's lounge at the India International Trade Fair in New Delhi on 16 November 2026, said stakeholders' suggestions on long-term capital gains (LTCG) tax and securities transaction tax (STT) were being examined in pre-Budget meetings. "We would consider them, and I'm sure that on February 1, you will get to know. Ultimately, an analysis is being done," he said, as reported by ANI and Business Standard. We found no official transcript or release.
Verified factNo change to LTCG or STT has been announced. We found no Finance Ministry or CBDT release proposing one, and the Chairman's remarks do not commit to any change.
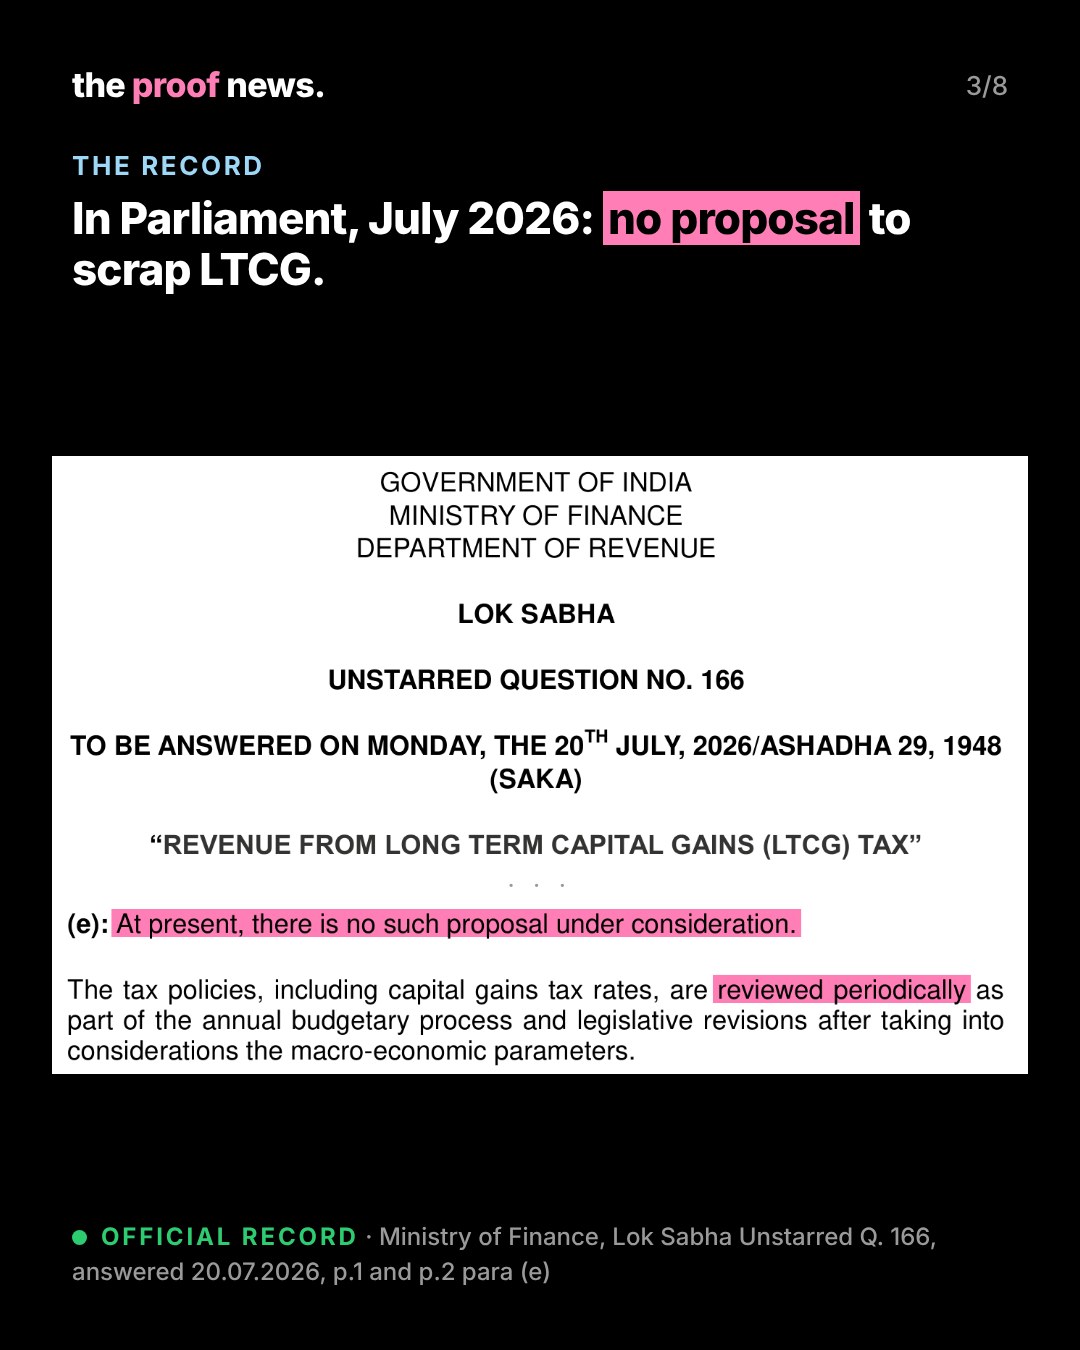
Official recordThe government's last statement in Parliament: on 20 July 2026, asked in the Lok Sabha when LTCG would be scrapped for retail and domestic investors, Minister of State for Finance Pankaj Chaudhary replied: "At present, there is no such proposal under consideration. The tax policies, including capital gains tax rates, are reviewed periodically as part of the annual budgetary process" (Unstarred Question 166, para (e)). The same answer says the 12.5% rate on equity LTCG is the same for foreign portfolio investors; a 2026 ordinance exempted their income only from government securities.
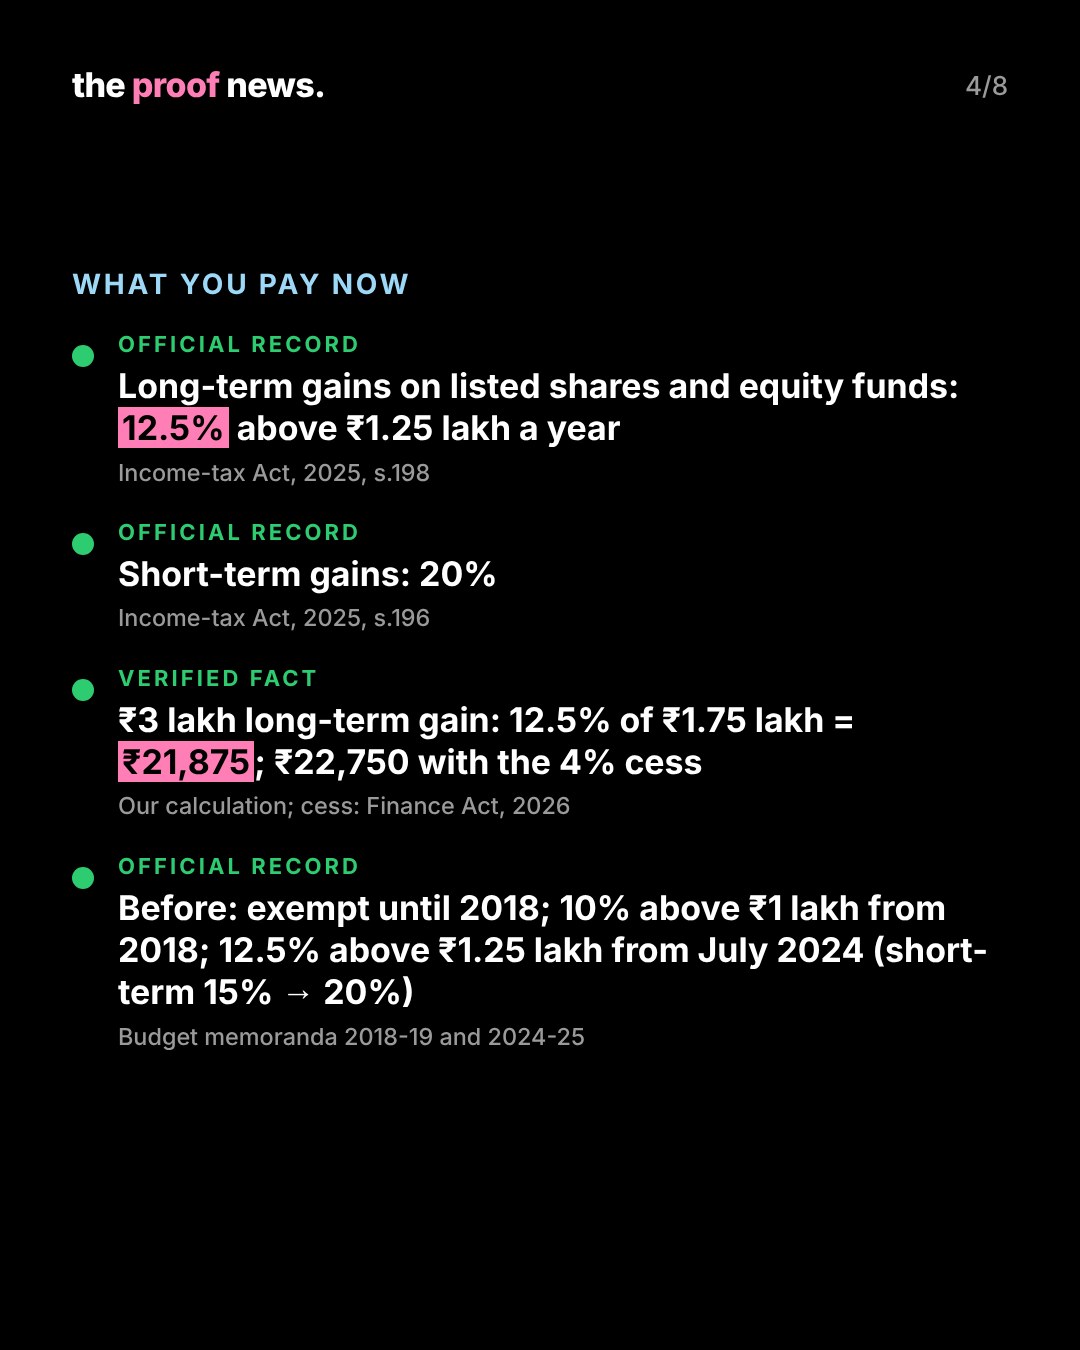
Official recordWhat investors pay now: under the Income-tax Act, 2025, long-term gains on listed equity shares, equity-oriented fund units and business-trust units, where STT has been paid, are taxed at 12.5% on gains above ₹1.25 lakh a year (section 198). Short-term gains on such assets are taxed at 20% (section 196). Health and education cess of 4% applies on top (Finance Act, 2026).
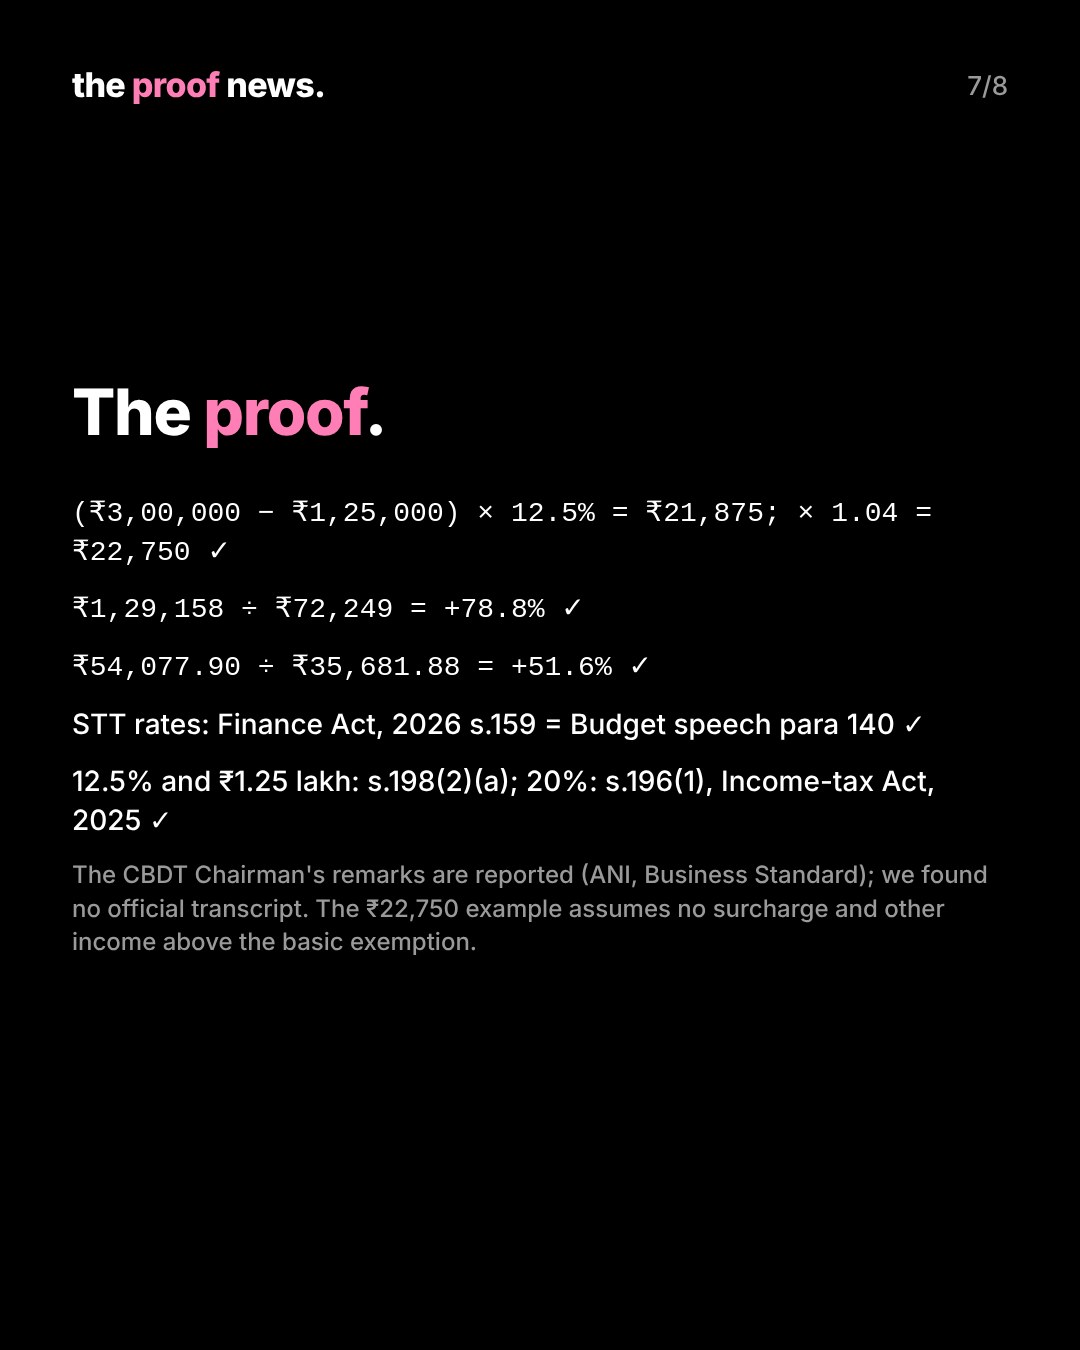
Verified factExample: a long-term gain of ₹3 lakh is taxed on ₹1.75 lakh at 12.5%: ₹21,875, or ₹22,750 with cess, assuming no surcharge and other income above the basic exemption.
Official recordHow the rates got here: long-term gains on listed shares were exempt until the Finance Act, 2018 withdrew the exemption and introduced a 10% tax on gains above ₹1 lakh. The July 2024 Budget raised it to 12.5%, raised the exemption to ₹1.25 lakh, and raised the short-term rate from 15% to 20% (Budget memoranda, 2018-19 and 2024-25).
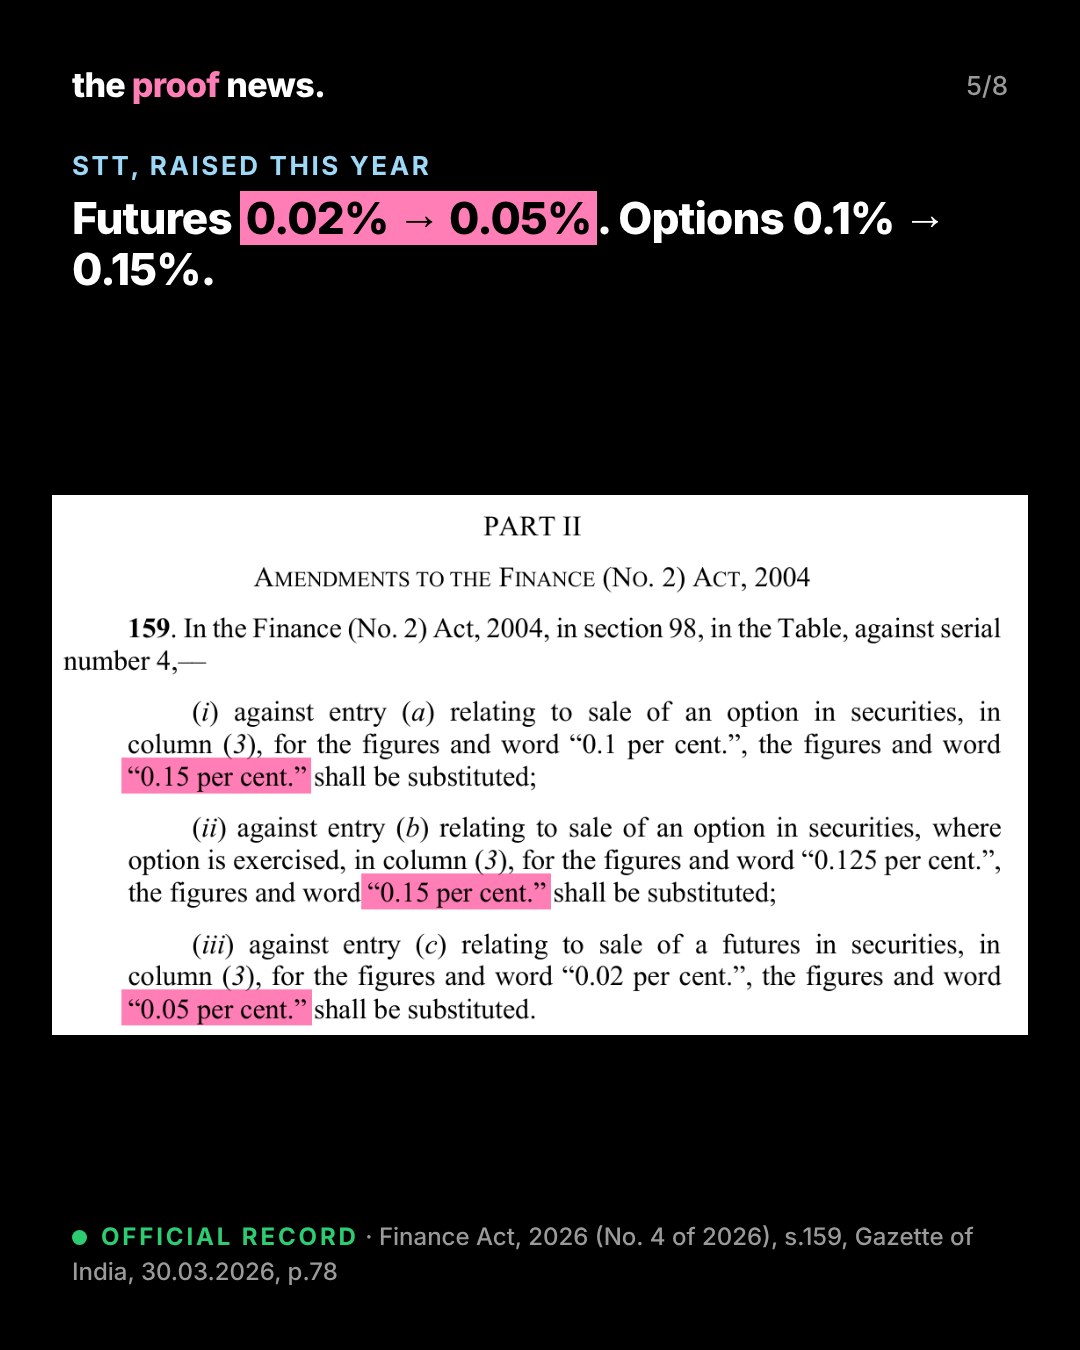
Official recordSTT was raised this year. The Finance Act, 2026 (section 159) raised STT on the sale of options from 0.1% to 0.15% of the premium, on exercised options from 0.125% to 0.15% of the intrinsic price, and on futures from 0.02% to 0.05% of the traded price. The Budget memorandum says the new rates apply to transactions from 1 April 2026, to "address issue of disproportionate increase in speculation in futures and options trading".
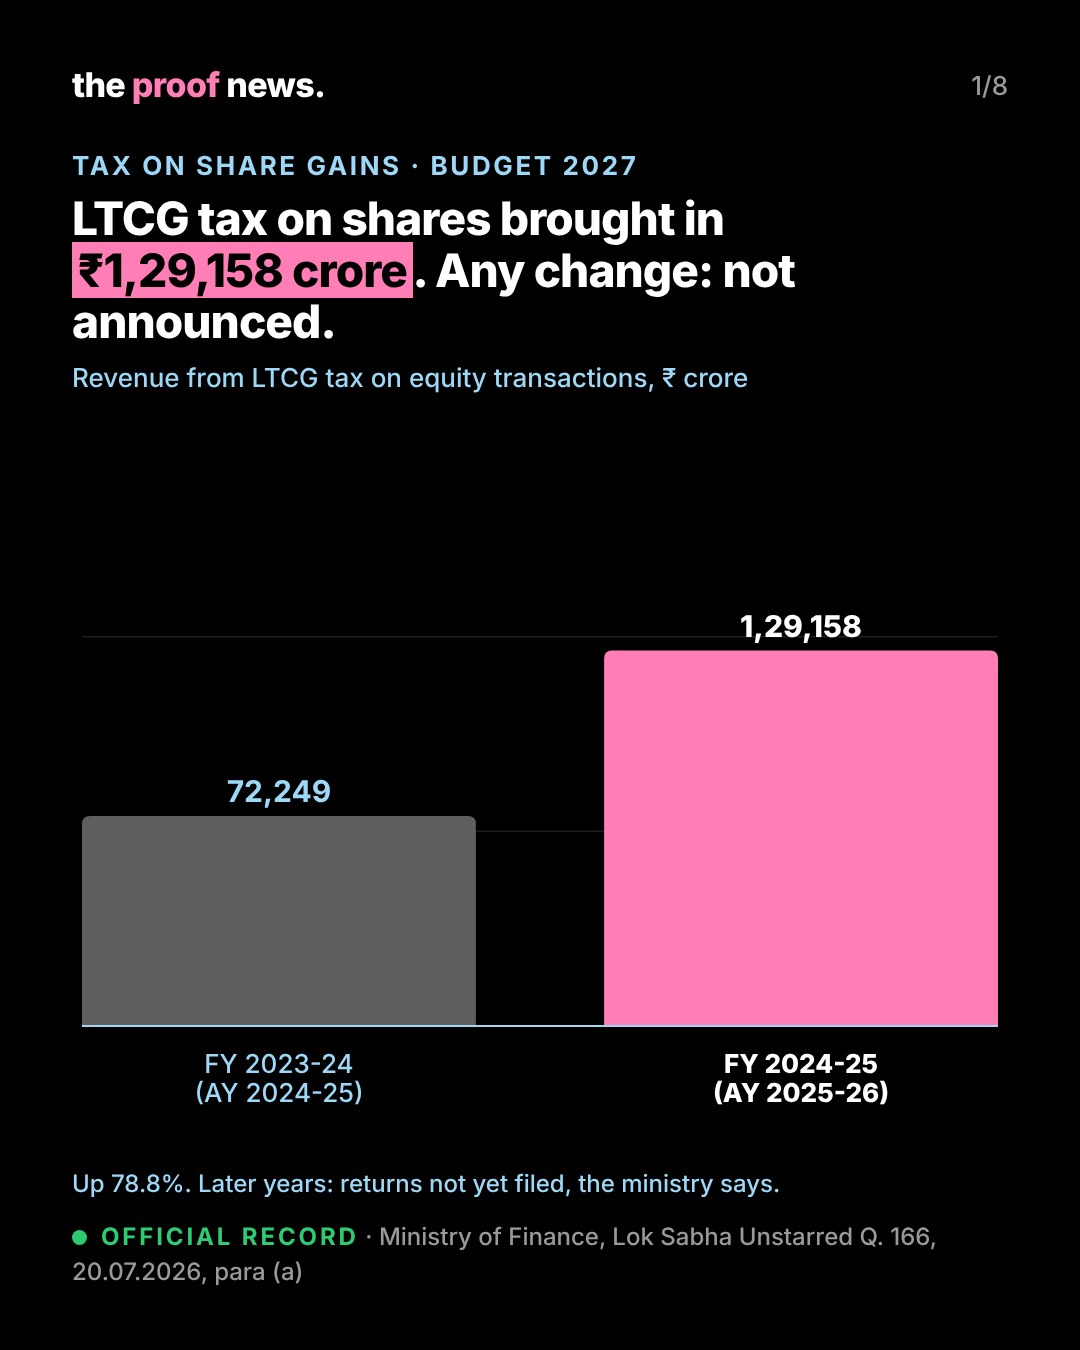
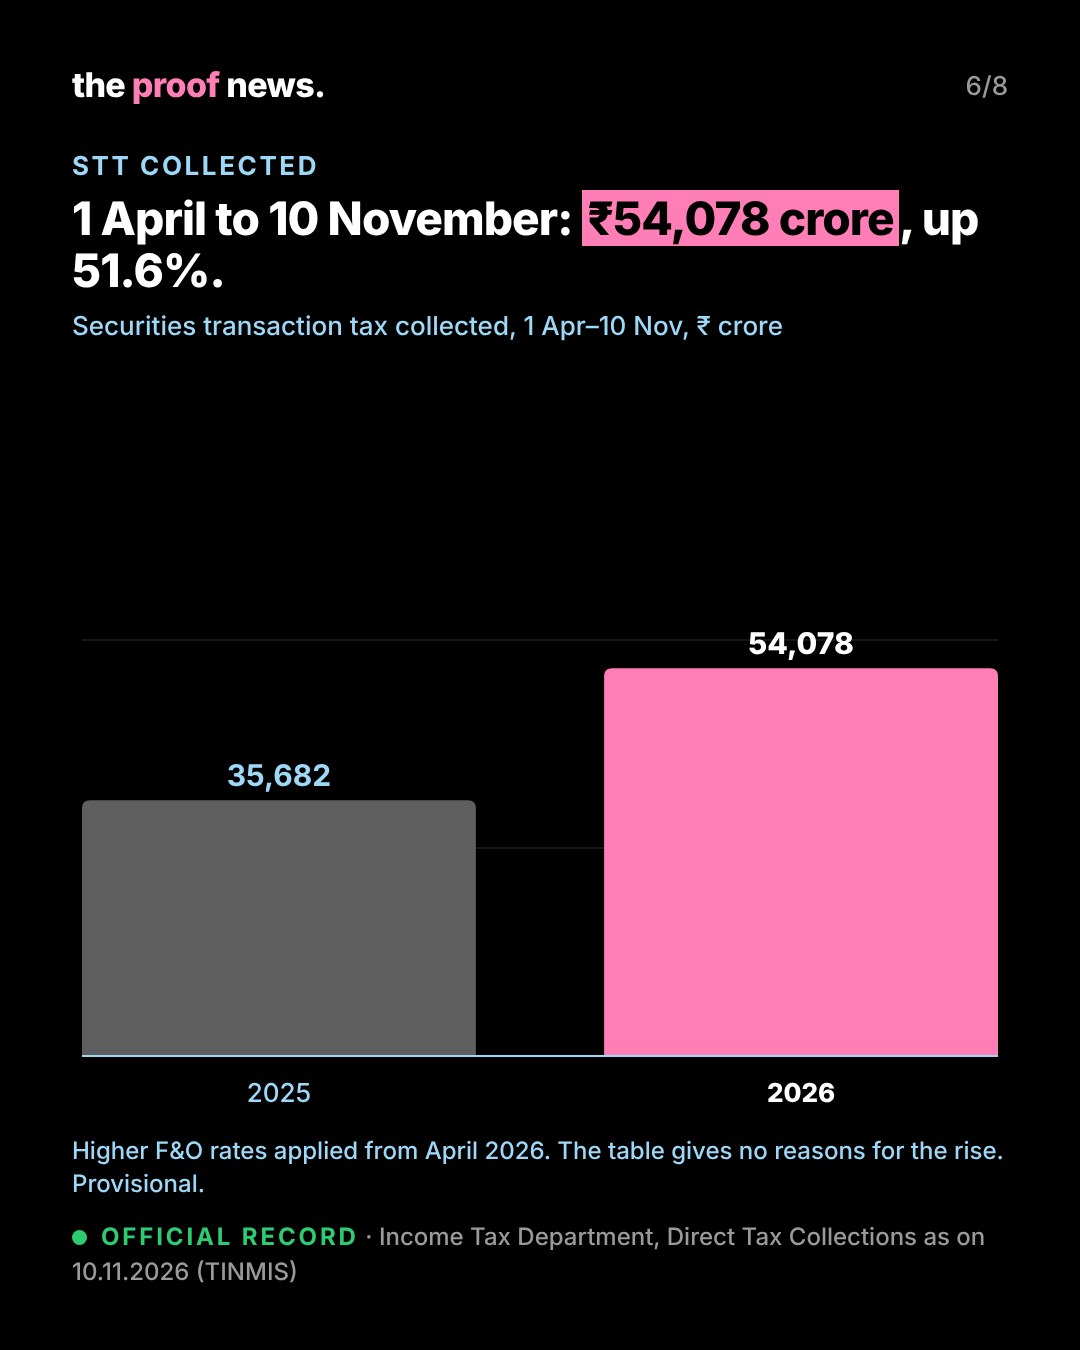
Official recordThe money: revenue from LTCG tax on equity transactions was ₹72,249 crore for assessment year 2024-25 (financial year 2023-24) and ₹1,29,158 crore for 2025-26 (financial year 2024-25), up 78.8% (Lok Sabha answer). STT collected from 1 April to 10 November 2026 was ₹54,077.90 crore, against ₹35,681.88 crore in the same period of 2025, up 51.6% (Income Tax Department, provisional). The table gives no reasons for the rise.
CommentaryMarket participants and industry chambers have asked for lower LTCG and STT rates, as reported; these are their proposals, not the government's. What to watch: the Union Budget, which the CBDT Chairman pointed to on 1 February 2027.
The proof.
Every rate is copied from the law: 12.5% above ₹1.25 lakh (Income-tax Act, 2025, s.198(2)(a)), 20% (s.196(1)), STT rates (Finance Act, 2026, s.159, identical to Budget speech para 140). Example: (₹3,00,000 − ₹1,25,000) × 12.5% = ₹21,875; × 1.04 = ₹22,750. LTCG revenue ₹1,29,158 / ₹72,249 = +78.8%. STT ₹54,077.90 / ₹35,681.88 = +51.6%.
- Ministry of Finance, Lok Sabha Unstarred Question 166, answered 20.07.2026 (PDF)
- Income-tax Act, 2025, section 198 (Income Tax Department)
- Income-tax Act, 2025, section 196 (Income Tax Department)
- Budget 2026-27: Finance Minister's speech (PDF)
- Budget 2026-27: Memorandum explaining the provisions of the Finance Bill (PDF)
- Budget 2024-25: Memorandum explaining the provisions of the Finance (No. 2) Bill (PDF)
- Income Tax Department, Direct Tax Collections as on 10.11.2026 (PDF)
- ANI, CBDT Chairman on LTCG and STT, 16.11.2026
- Business Standard, CBDT chief says LTCG, STT proposals under review, 16.11.2026